
Money App - Cash Advance
- Rating
- 4.2
- Downloads
- 500.00K
- Content Rating
- Everyone
Money App - Cash Advance - Screenshots
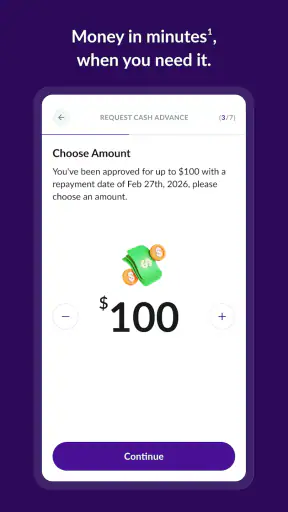
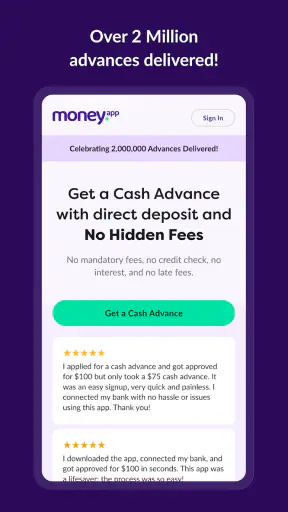
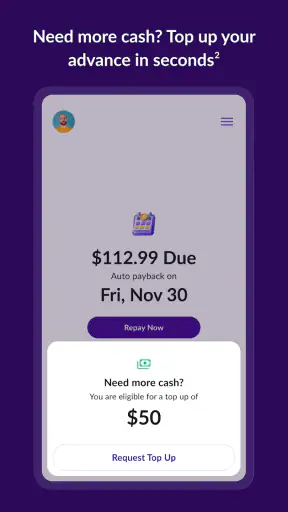
Pros
- Simple application process with minimal paperwork
- Fast eligibility checks can provide quick access to funds
- Repayment terms and fees are shown before accepting an offer
- Useful for covering unexpected short-term expenses
- Available application tracking helps monitor your request
Cons
- Approval and advance amounts depend on your financial profile
- Fees and interest may make borrowing expensive
- Late repayments could lead to additional charges
- Not available in every country or state
- May require access to sensitive personal and financial data
Money App - Cash Advance - Description
- App Name
- Money App - Cash Advance
- Package Name
- com.prgventures.moneyapp
- Developer
- PRG Ventures.
- Category
- Finance
- Last Updated
- Feb 12, 2024
- Version
- 2.48.0
When an unexpected bill lands between paydays, the problem is rarely complicated in theory: I need access to cash quickly, and I need to understand exactly what I am agreeing to. Money App - Cash Advance is built around that emergency-cash use case rather than trying to be a complete banking replacement. After spending time with it, I see its main value in the way it puts a short-term cash request at the center of the experience. That focus can be useful when timing matters, but it also means the app deserves a more careful look than a simple “free finance app” label suggests.
Developed by PRG Ventures, this free finance app is aimed at adults and carries an Everyone content rating. It has attracted over 500 thousand installs, with an average rating of 4.2 from around 10 thousand ratings and roughly 2.4 thousand written reviews. Those figures suggest that many people find the basic idea worthwhile, while the written feedback also points to the kind of product where personal circumstances can strongly affect the experience.
Emergency cash is the capability that defines the experience
The most important thing to understand is that Money App is not primarily a budgeting diary, investment dashboard, or traditional checking account. Its identity comes from helping users pursue emergency cash through a mobile workflow. That distinction matters because the app makes the most sense when the question is, “How can I handle a short gap right now?” It makes less sense if your real goal is to build savings, track every category of spending, or replace a full-service bank.
I like this focused approach because financial stress often makes complicated interfaces harder to use. A person dealing with a late utility payment or an urgent household expense does not necessarily want to explore a long list of financial tools. The useful effect of the cash-advance focus is that it keeps attention on the immediate task. At the same time, a focused interface should not be mistaken for guaranteed approval or guaranteed access to money. A request is still part of a financial decision, and the result can depend on eligibility and the information requested during the process.
The practical strength is speed of orientation, not a promise that every request will end with cash. That is the mindset I would bring to the app. It can help you investigate an emergency-cash option from your phone, but I would never treat it as money already in my account until the process clearly confirms that outcome.
What the app is really good at
Its best role is as a first stop when an expense is urgent but relatively contained. For example, imagine that your car needs a repair before you can get to work, and your normal payday is still several days away. Money App gives you a place to explore a cash-advance route without immediately visiting a branch or calling several lenders. That convenience can reduce the time spent searching, especially when you are already juggling work and household responsibilities.
There is also a psychological benefit to having the request process in one mobile setting. I found it easier to think through the situation when I could pause, review what I was entering, and decide whether the proposed option actually solved the problem. That pause is important. A simple-looking request can still create a repayment obligation, and convenience should not remove the habit of checking the full terms before proceeding.
How I would use it in practice
I would begin by treating the app as an eligibility and emergency-cash tool, not as a source of routine spending money. The first step is to install it on a compatible Android device and open the request flow when I can concentrate. The listed minimum operating-system requirement is Android 7.0, so older phones may not be suitable. The current version is 2.48.0, which is useful context when comparing the experience on devices that have not been updated recently.
When entering personal and financial information, I would slow down rather than rushing because the situation feels urgent. I would keep the details consistent, read each screen, and check whether the amount being considered is genuinely necessary. One of the more useful habits here is to decide the repayment source before submitting anything. If I cannot identify which future income will cover the obligation, I would see that as a warning to stop and consider another option.
I would also compare the total cost and timing with alternatives before accepting an offer. The app is free to download, but that does not automatically mean every financial option presented through a cash-advance service is cost-free. Those are two separate questions. The download price tells me about access to the app; it does not answer what a particular advance may require. I would look for the complete repayment amount, any applicable charges, and the expected timing before making a final decision.
Another practical tip is to avoid submitting multiple requests while waiting for one result. When someone is anxious, it is tempting to keep tapping through different services. That can make the overall situation harder to track and may lead to accepting more than is comfortable. I would use Money App to investigate one realistic amount, record what I am being offered, and then compare it with a bank overdraft option, a payment extension, or help from a trusted person.
A realistic emergency scenario
Suppose I have an essential expense due tomorrow and enough income arriving next week to cover it. In that situation, the app could be useful because it gives me a mobile route to examine emergency cash without turning the problem into a long-term financial plan. I would calculate the exact shortfall, not request a vague cushion, and keep the amount as small as the expense allows. The smaller the request, the easier it is to judge whether the repayment fits the next pay cycle.
Before continuing, I would ask myself three questions. Can I cover the repayment without missing another bill? Do I understand the full cost and timing? What happens if my income arrives late? If any answer is unclear, I would not rely on the app as the solution. In this scenario, the app’s convenience is valuable only when it supports a repayment plan that is already realistic.
This is also where Money App differs from a standard budgeting app. A budgeting tool might help me identify the shortfall and cut unnecessary spending, but it usually does not address the immediate request for cash. A bank might offer a more established borrowing route, but its process may be less convenient or less suited to a small, time-sensitive gap. Money App sits between those experiences: more direct than planning software, but not a substitute for a bank relationship or a stable emergency fund.
Where the convenience becomes a trade-off
The biggest limitation is the risk of treating emergency access as normal income. If I use a cash-advance service repeatedly for groceries, subscriptions, or ordinary monthly bills, the app may make the symptom easier to manage while leaving the underlying shortfall untouched. That is not a flaw unique to this product, but the streamlined mobile experience can make repeated use feel less serious than it is.
I would also be cautious about making a decision while under pressure. A phone-based process is private and convenient, but it can encourage quick acceptance. The right comparison is not simply “cash now versus no cash.” It is “cash now versus the total amount I will need to repay, the date it will leave my finances, and the consequences if my next income is smaller than expected.” That calculation should happen before acceptance, not afterward.
Another trade-off involves expectations. The store summary presents the app as a way to get emergency cash, but I would interpret that as the purpose of the service rather than a guarantee. Approval, available amounts, and final terms can vary by the individual situation and the request process. Anyone who needs a definite amount by a definite hour should keep a backup plan instead of assuming the app will solve the problem on demand.
Compared with asking a bank for a personal loan, Money App may feel less cumbersome for a short-term need, but a bank or credit union can be the better choice when the amount is larger, the repayment period is longer, or the borrower wants a more familiar ongoing relationship. Compared with a credit card, the app may be more targeted to a cash gap, while a card can offer a clearer existing limit for someone who already understands its terms. Compared with borrowing from family, it may feel more private, although a personal conversation could avoid certain financial costs. The best alternative depends on the emergency, not on which app opens fastest.
Small workflow choices that make a difference
My first recommendation is to prepare before opening the request form. Have the bill amount, due date, and expected repayment source in mind. This prevents the common mistake of requesting more simply because the option appears available. It also makes it easier to reject an amount that would create unnecessary pressure.
Second, read the confirmation screens as carefully as the initial request screens. The early part of a financial app can feel like a questionnaire, while the final step is where the practical commitment becomes clearer. I would take a screenshot or keep a private note of the amount, repayment date, and total obligation if the app presents those details, so I could refer back to them without relying on memory.
Third, separate the app’s usefulness from the quality of the financial decision. Money App can make it easier to explore an option, but it cannot decide whether that option fits my budget. I would use a simple test: after the repayment, can I still cover housing, food, transport, and other essential bills? If the answer is no, the emergency cash may only move the crisis forward by a few days.
Finally, I would review the app after the immediate problem is over. If I needed it because of a one-time event, I could uninstall it or simply stop using it once the situation was resolved. If I needed it repeatedly, that pattern would tell me to look for a longer-term solution such as changing bill dates, building a small buffer, negotiating payment timing, or seeking nonprofit financial guidance. The app can be part of a short-term response, but it should not become the entire financial plan.
Who gets the most value from Money App
The strongest fit is someone with a temporary cash gap, a clear source of upcoming income, and enough discipline to review the terms before accepting anything. That person may appreciate being able to start the process from a phone and compare the emergency option with other choices without immediately committing. The app is also approachable for someone who does not want a complex investment or budgeting platform when the immediate issue is simply a bill due soon.
It is a weaker fit for anyone looking for guaranteed money, long-term debt management, or a replacement for a bank account. I would also advise caution if your income is unpredictable, your existing bills already consume nearly everything you earn, or you are considering an advance to pay back another advance. In those cases, the central convenience can hide a cycle rather than solve the original problem.
The Everyone rating describes broad store accessibility, not a promise that every financial situation is suitable. I would still expect users to make adult decisions about borrowing, repayment, privacy, and affordability. A finance app can be easy to open while the consequences of a poor decision remain difficult to undo.
My final view after looking at the full use case
Money App - Cash Advance does one thing clearly: it gives people a mobile way to explore emergency cash when ordinary timing is the problem. I appreciate that focus, and I can see why the app has reached more than 500 thousand installs and maintained a 4.2 average rating. The experience is most convincing when the need is specific, temporary, and backed by a realistic repayment plan.
My recommendation is conditional rather than automatic. I would consider it for a genuine shortfall after checking the total obligation and comparing alternatives. I would skip it for routine expenses, uncertain income, or any situation where repayment would simply create the next emergency. PRG Ventures has made a focused finance app, but the app’s convenience should be paired with careful judgment. Used as a controlled way to investigate a short-term option, it can be useful; used as a substitute for stable finances, it is the wrong tool.
FAQ
What is Money App - Cash Advance, and how does it work?
Money App - Cash Advance is designed to help eligible users request a small amount of money before their regular payday. After creating an account, you generally provide personal, employment, income, and banking information so the service can assess eligibility. If approved, the advance may be sent to a linked bank account or debit card. Availability, limits, and repayment terms can vary by user and location.
How much money can I borrow, and what are the costs?
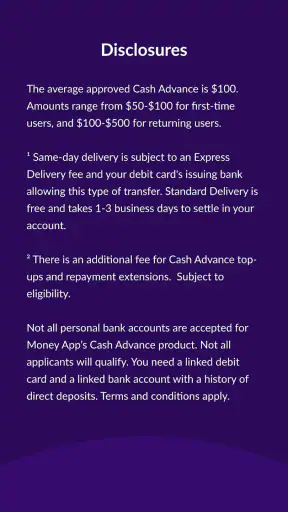
The amount available through Money App - Cash Advance depends on factors such as your income, account history, repayment behavior, and the information verified during registration. Before accepting an advance, carefully review the total repayment amount, subscription charges, optional fees, expedited-transfer costs, and any other applicable expenses. A cash advance is not free money, so compare the full cost with other borrowing options.
What information and permissions does the app require?
To evaluate an application and manage repayments, Money App - Cash Advance may request details such as your identity, contact information, income, employment, bank account, and debit-card data. Depending on the features enabled, it may also request access to financial or device information. Read the privacy policy and permission prompts carefully, and only submit information through the official app or website. Never share banking passwords or verification codes unnecessarily.
When will I receive the cash advance, and how is it repaid?
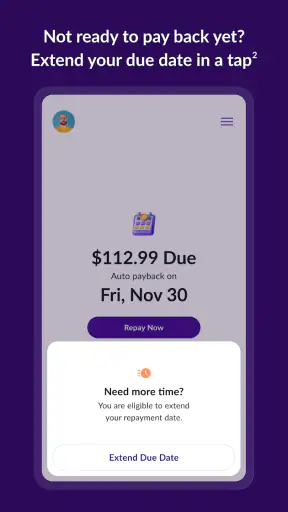
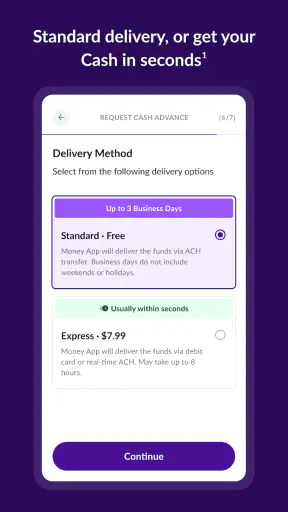
Processing and delivery times depend on approval, bank processing, the transfer method selected, weekends, and holidays. Standard delivery may take longer, while an expedited option could involve an additional fee. Repayment is commonly scheduled for a future payday or another date shown in the agreement and may be collected automatically from a linked account. Confirm the repayment date and keep enough funds available to avoid overdrafts or failed payments.
Is Money App - Cash Advance safe, and who should avoid using it?
Use the official store listing, verify the developer, and review the app’s privacy, security, and lending disclosures before registering. The service may be useful for a genuine short-term emergency, but it should not replace regular budgeting or long-term financial planning. Avoid using it if you cannot comfortably repay on time, are already relying on multiple advances, or do not understand the fees and authorization terms. Late or failed repayment may create additional financial problems.


